You're Not Behind: Why Your 20s Are the Right Time to Start With Money
Feeling behind financially? Here's why the "everyone has it figured out" story isn't true, and the small first money moves that matter most in your 20s.
Key points: The feeling of being behind is common, and it's built on three myths that don't hold up. Your 20s are one of the best times to start, even with a small paycheck.
Who it's for: You, if you're in your 20s, scrolling past finance videos and quietly wondering if you've already missed your chance.
What you'll walk away with: The facts behind the myths, and three small first moves you can make this week.
Scroll for five minutes and you'll find someone your age who has paid off their loans, bought a condo, and maxed out a retirement account. Then you open your banking app, close it again, and think: I'm already behind, and I don't even know where to start.
If that's you, take a breath. Feeling behind financially is one of the most common money feelings there is, and it's built on a few stories that sound true but aren't. Let's take them apart, one at a time.
Myth 1: "Everyone else my age already has this figured out."
The fact: You're comparing your behind-the-scenes to everyone else's highlight reel.
What you see online is a sliver of someone's life, often chosen because it looks impressive. You don't see the parent who helped with the down payment, the credit card balance, or the years of trial and error. Most of the friends you think have it handled are figuring it out as they go, just like you.
Feeling behind is a sign you care, not a sign you've failed. That feeling is actually useful: it's the push that gets you started.
Myth 2: "I'll deal with money later, once I make more."
The fact: Starting small now often matters more than starting big later.
Here's why. Compound growth is what happens when the money you save earns a return, and then that return earns a return too. Over time, growth builds on growth. The biggest ingredient isn't how much you put in. It's how much time the money has to grow.
A simple illustration: if you set aside $50 a month starting at 25, and it grew at an average of 6% a year, you'd have put in about $24,000 of your own money by 65, and it could grow to roughly $100,000. (That's a hypothetical example, not a promise. Real returns go up and down, and no one can guarantee them.)
Time is the one advantage your 20s give you that no raise can buy later. And habits matter as much as dollars. The routine you build with $50 a month is the same routine that handles $500 a month down the road.
Myth 3: "Money stuff is too confusing for me."
The fact: You don't need to understand everything. You need to understand the next thing.
Personal finance looks complicated because it's often explained in jargon by someone trying to sound smart. Underneath, the first steps are simple:
A budget is just a plan for where your money goes each month, made before the month happens.
An emergency fund is money set aside only for surprises, like a car repair or a surprise bill, so they don't end up on a credit card.
An employer match is money your employer adds to your retirement account when you contribute. If your job offers one, it's part of your pay, and claiming it is one of the easiest wins available.
That's enough to start. Nobody learns money all at once. You learn it one decision at a time.
What Starting Actually Looks Like
Starting doesn't mean overhauling your life or downloading five apps. It means three small moves:
Look without judging. Open your bank account and write down what's in checking, what's in savings, and any balances you owe. You're not grading yourself. You're finding your starting point.
Pick one tiny automatic habit. Set up a $10 or $20 weekly transfer into a separate savings account. Small enough to forget about, big enough to build momentum.
Check one benefit. If you have a job with benefits, find out whether it offers a retirement match. If it does, ask HR how to contribute enough to get all of it.
None of these take more than 20 minutes. Together, they move you from "I don't know where to start" to "I've started."
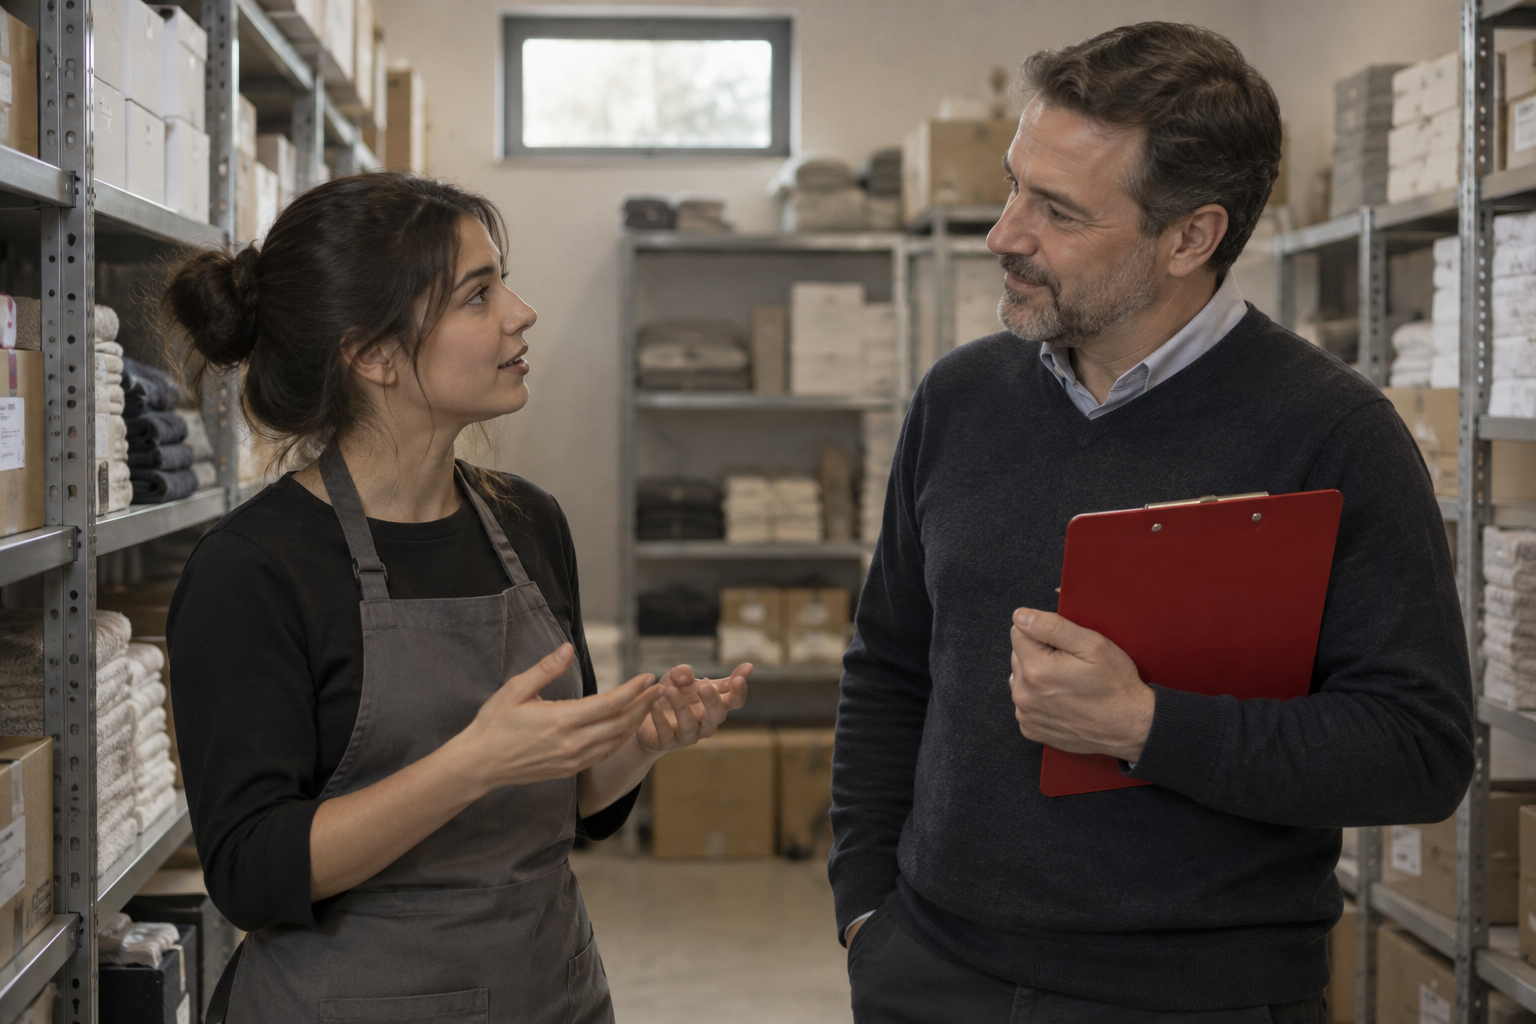
Young woman at her part-time job asking her manager about the retirement match
Why This Is About More Than Money
At Infinite Investor, we see money as one part of a bigger picture we call The Seven Pillars of Personal Investment. One of them is Faith: your purpose, mindset, and the beliefs that shape who you are. The story "I'm behind" is a belief, and beliefs can change.
When you swap "I'm behind" for "I'm starting," your choices start to follow. You stop avoiding your bank app. You start asking questions. The most valuable investment you can make right now is in how you see yourself with money.
Your Next Step
This week, do the first move on the list: open your accounts and write down your three numbers (checking, savings, and anything you owe). That's it. You'll have done more than the version of you who kept scrolling.
Once you've started, the next step is building a simple weekly habit that keeps your money on track without taking over your life.
You're not behind. You're right on time to begin.
Haven't grabbed your copy yet? Download You're Not Behind: Your First 90 Days of Getting Your Money Together and get the roadmap for free.
This article is general education, not individual financial advice. For decisions about your personal situation, consider talking with a qualified, fee-only financial professional.